

CONTRIBUTORS

Noelle Tune, MD
Analyst
Putnam Investments
Biotechnology investing has been a wild, and often frustrating, endeavor since the March 2021 highs in the midst of the COVID-19 vaccine rollout. The good news? Remarkable innovation provides abundant opportunities for investors who know the biotech space and are able to conduct deep fundamental research.
My experience as an emergency medicine physician offers perspective in my research. It’s the hat I put on when I initially screen for investments. In my equity analysis, I focus on which diseases need better treatments, and which businesses are best equipped to provide them. I look for companies with the most innovative approaches, the most intriguing pipelines, and a commitment to solving a problem that currently has no solution.
Signs point to improvement for the sector in 2025
Over the past five years, the biotechnology sector has significantly underperformed the broader market and, in particular, technology stocks. The most recent lackluster returns can be tied to headwinds such as persistently high interest rates and concerns over health-care policy changes with the Trump administration. Another headwind is the more longstanding need for consolidation following the rash of biotech IPOs during the COVID-19 pandemic. Despite the uncertainty, biotech continues to offer exciting possibilities—for investors as well as for individuals in need of innovative treatments. The sector has the potential to right itself in 2025, particularly if we see an acceleration of merger-and-acquisition activity, a stable regulatory environment, and gradually easing interest rates. Importantly, we see a lot of fundamentally compelling stocks at attractive valuations after the recent drawdown.
Uptick in M&A activity is worth watching
On the M&A front, year to date, we have already seen a proposed M&A deal—Johnson & Johnson’s proposed purchase of Intra-Cellular Therapies in early January. This one deal is larger than the top four deals in 2024 combined, renewing hope that 2025 will see a more active deal calendar.
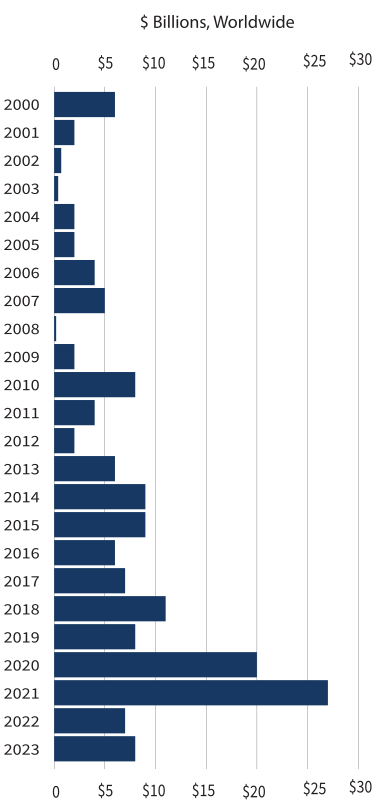
More deal flow is needed to re-invigorate biotech, however. Despite consolidation over the past few years, there are still too many small, under-capitalized companies, many of which came public during the pandemic-influenced years of 2020 and 2021. A return to 2023 M&A volumes in 2025 would go a long way to boosting generalist interest in the sector.
Pandemic era brought a rise in biotech IPO volumes
Source: Data from CapitalIQ and Stifel database as of December 2024.
Keeping an eye on political and headline risks
Concerns exist around several nominees for health care leadership posts. Most notable, especially for vaccine players, is the appointment of Robert F. Kennedy Jr. for Health and Human Services secretary. However, the nominee for FDA commissioner, Dr. Marty Makary, a physician/scientist, appears to be viewed positively by industry personnel. This could bode well for stability of FDA staffing and continued improvements in the pace of drug approvals following labor-related constraints during the pandemic. While risks remain around FDA uncertainties, I am hopeful that we will look back on 2025 and note that FDA operated in a business-as-usual, if not slightly improved, fashion.
Persistent demand boosts opportunities for biotech investors
I’ll paraphrase a colleague, who said recently that biotech may not always be profitable, but at least it’s interesting. Our goal is to make it interesting and profitable. We look for strong ideas in companies that are relatively de-risked and innovative. While we stay cognizant of macroeconomic headwinds, we don’t let them interfere with our focus on fundamentals. We believe there are many reasons to be excited about investing in biotech in the coming years.
Watch for my thoughts on the most compelling biotech opportunities in a future Equity Insights post.
Endnotes
-
Indexes are unmanaged and one cannot directly invest in them. They do not include fees, expenses or sales charges. Past performance is not an indicator or guarantee of future results.
WHAT ARE THE RISKS?
All investments involve risks, including possible loss of principal.
Equity securities are subject to price fluctuation and possible loss of principal.
Investments in fast-growing industries like the health care sector could result in increased price fluctuation, especially over the short term, due to the rapid pace of product change and development and changes in government regulation of companies emphasizing scientific or technological advancement or regulatory approval for new drugs and medical instruments.
Active management does not ensure gains or protect against market declines.
Any companies and/or case studies referenced herein are used solely for illustrative purposes; any investment may or may not be currently held by any portfolio advised by Franklin Templeton. The information provided is not a recommendation or individual investment advice for any particular security, strategy, or investment product and is not an indication of the trading intent of any Franklin Templeton managed portfolio.
